

Sunright’s operating recovery cleared the downside tests we set for it in May.

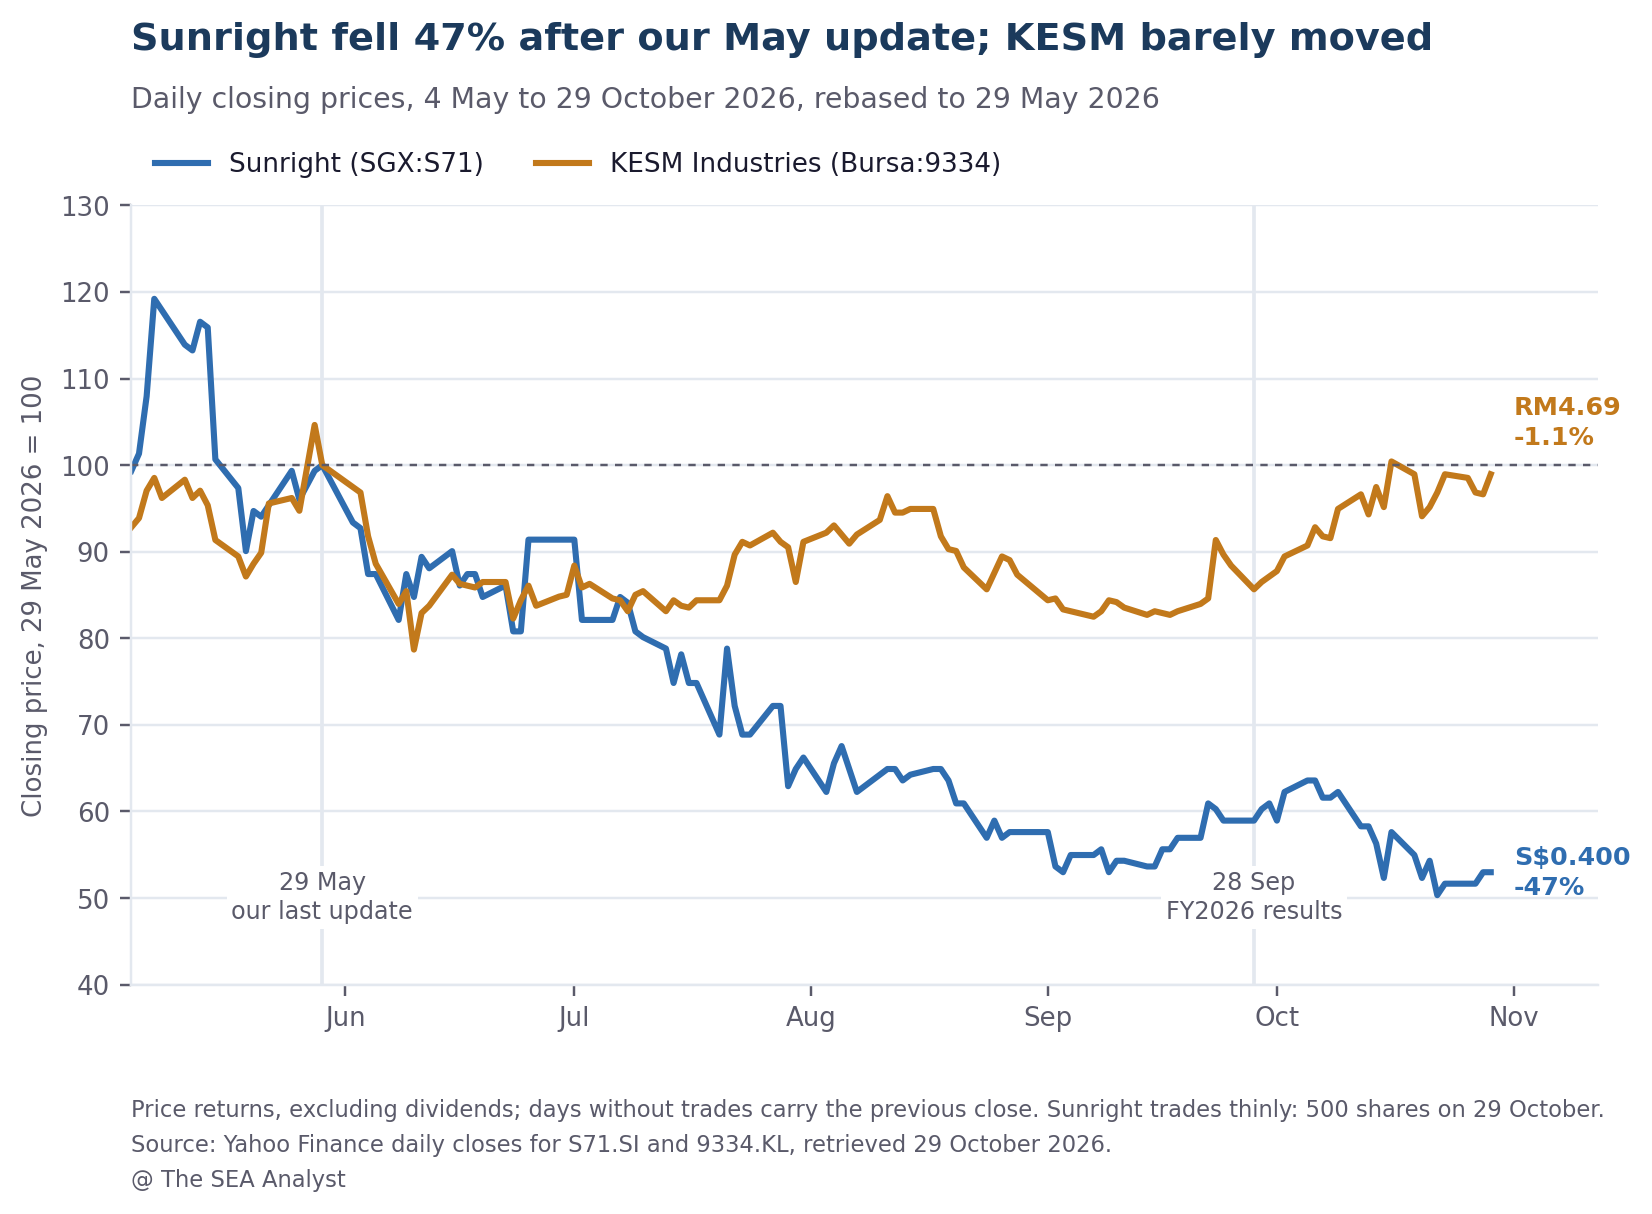
Revenue for the year to 31 July 2026 rose 17.7% to S$85.9 million, profit attributable to shareholders came in at S$1.4 million against a S$5.8 million loss [1], and KESM Industries, the Bursa-listed subsidiary that produces most of the group’s revenue, returned to profit, with revenue growth it attributed to demand for AI-related chips [2]. The shares went the other way. Sunright closed at S$0.400 on 29 October, 47% below the S$0.755 close cited in our 31 May update, and below both the S$0.59 bear case and the net-cash floor we described at initiation [3,4,5]. KESM closed the same day at RM4.69, almost exactly where it was in May.
The fall did not wait for the results. Sunright closed at S$0.69 at the end of June, S$0.50 at the end of July and S$0.445 on 28 September, the day the full-year numbers were filed [3]. The annual report, released on 26 October, added the detail that matters for the question we raised in May: how much of KESM’s improving business actually reaches a Sunright shareholder.
What the profit is made of
Sunright’s chairman attributed the return to profit to stronger volumes, new solutions and operational discipline “whilst monetizing underperforming assets” [6]. The last clause is the one the accounts can size. Gains on selling equipment and assets held for sale rose from S$0.46 million to S$2.83 million, against profit before tax of S$4.04 million. Interest on the group’s deposits added another S$2.04 million. Take both out and the remainder is a loss of S$0.82 million.
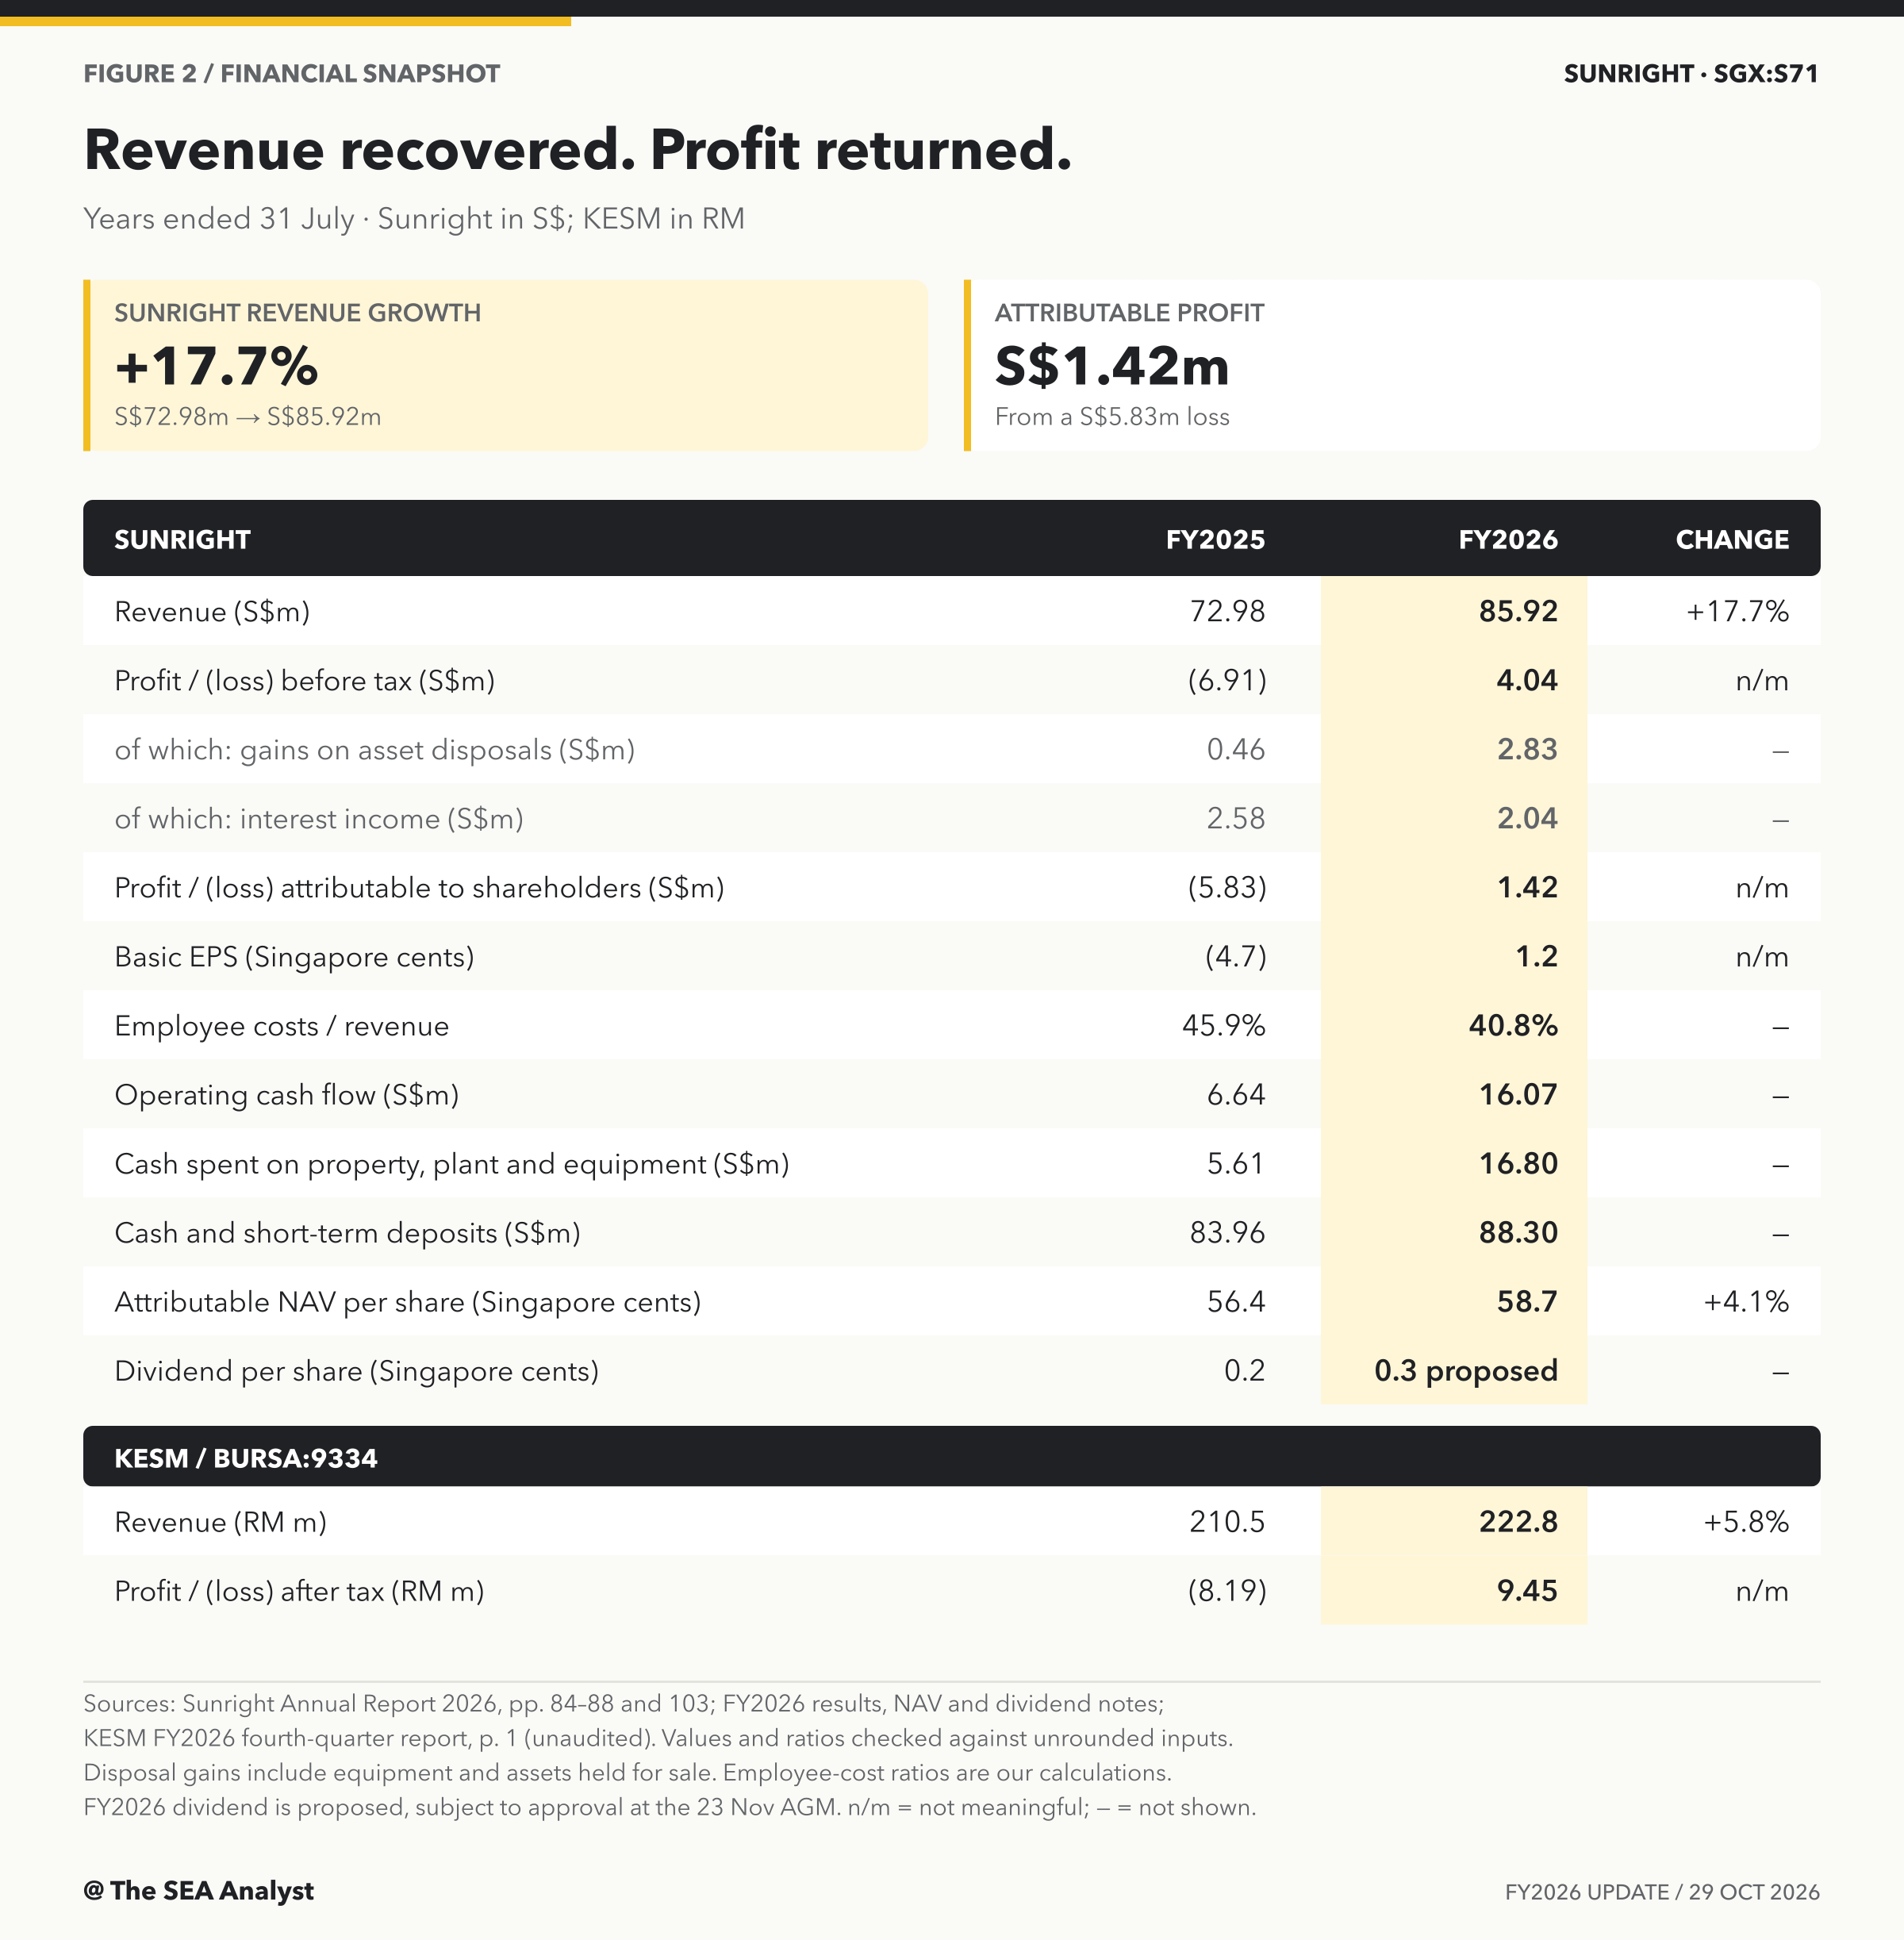
The S$0.82 million remainder is a sensitivity, not a measure of underlying profit: it leaves in finance costs, exchange losses and a S$0.25 million reversal of a receivables impairment, and it ignores tax and the minority share. Interest on S$88 million of deposits is real income, and selling idle equipment is a reasonable thing to do. But FY2026 does not yet establish that the operating business is sustainably profitable.
KESM’s numbers carry the same pattern. Its RM12.87 million profit before tax included RM8.34 million of disposal gains and RM5.76 million of interest. Other income also included RM1.2 million of compensation for unfulfilled minimum orders and RM1.0 million for accelerated deliveries [2]. The demand is real: KESM’s fourth-quarter revenue rose 14.9% to RM61.5 million, an increase KESM said was “largely driven by higher demand for our services in processing artificial intelligence” chips [2]. The profit is thinner than the headline.
Cash says the same. Operating cash flow of S$16.07 million fell S$0.74 million short of the S$16.80 million spent on equipment, and S$1.54 million of lease repayments widened the gap to S$2.27 million. Operating cash flow itself includes S$2.14 million of interest received and a S$0.40 million net tax refund. Additions to property, plant and equipment were S$23.58 million, S$6.78 million more than the cash paid. Part of that gap is new leases. Sunright attributes the S$9.0 million rise in trade and other payables “largely” to machinery and test equipment purchases, dividends payable and accrued expenses.
Corrections to our May coverage
Five statements in our May pieces were wrong, and two of them bear on the valuation. A sixth, our May measure of the premium itself, is revisited in the valuation section.
The first concerns the Texas environmental claim. On 10 May we wrote that Weatherford’s suit against Sunright’s US subsidiary “remains active as of the FY2025 annual report” [4]. It did not. Weatherford filed a notice of nonsuit, and on 10 October 2024 the Midland County court dismissed the claims against all defendants, including KES (USA) Inc., the predecessor of KES Systems, Inc. Sunright announced the dismissal on 11 and 25 October 2024, and note 30 of the FY2025 annual report records it [7,8]. The dismissal was without prejudice, so Weatherford can re-file, and Sunright has made no provision. The FY2026 annual report carries no litigation note.
The second is the floor. At initiation and again on 31 May we treated roughly S$0.55 a share of net cash as supporting the share price [4,5]. That figure is consolidated: it counts all of KESM’s cash, and KESM held RM217.4 million, about S$68 million, or 77% of the group’s S$88.3 million [2]. KESM’s other shareholders have a 51.59% economic interest in it. The parent company’s own balance sheet shows S$18.1 million of cash against S$5.2 million of borrowings, S$0.105 a share. Taking Sunright’s 48.41% of KESM’s net cash plus the parent and the wholly owned subsidiaries gives about S$39 million, or S$0.32 a share, on our calculation. None of these is a liquidation value, but S$0.32 is the closest of the three to Sunright’s proportionate claim on group cash, and the shares are only 26% above it.
The other three are smaller. Our 31 May update counted the 6-sen dividend KESM paid on 28 October 2025 as part of FY2026; KESM’s filing shows it was the FY2025 dividend [2,5]. Our 9 and 10 May pieces described the S$5.3 million of FY2025 Singapore revenue as a Singapore equipment business, and the 9 May piece called the parent loss-making at entity level; the S$5.3 million is revenue by customer location, the parent’s stated activities are investment holding and management services, and its own accounts show a profit of S$332,000 in FY2025 and S$372,000 in FY2026 [4,9]. The 9 May piece put FY2025 dividends leaving the group at S$5.5 million; actual FY2025 cash dividends leaving the group were S$504,000, all paid to KESM’s minority shareholders [9]. In FY2026 payments to those minorities rose to S$839,000; including S$246,000 paid to Sunright shareholders, total external dividends were S$1.085 million.
Sunright’s profit is KESM’s profit
Sunright’s 48.41% of KESM’s FY2026 profit comes to about S$1.44 million in Sunright’s own accounts, derived from the S$1.54 million the group allocated to KESM’s minority shareholders. Sunright’s attributable profit was S$1.42 million. Everything outside KESM, from the parent company to the wholly owned equipment, US and Philippine subsidiaries, contributed roughly nothing to what shareholders earned in FY2026, on our calculation, and that is after the parent’s fee income from KESM.
That changes what the Sunright share price has to be measuring. In May the argument was that the SGX listing carried a premium for a parent business the Bursa listing did not see. The FY2026 accounts show the businesses outside KESM breaking even, and a share of KESM that earns the group’s entire profit.
Below the break: Sunright’s holdings outside KESM now trade at S$18.3 million, 0.92 times estimated book and close to the parent’s S$17.7 million of net cash and one receivable. KESM paid Sunright RM9.96 million in cost-plus management fees, with the mark-up undisclosed. And one of our May tests fired on its wording but not its logic, while all three bull-case thresholds were missed.